Selling a parent’s home isn’t the only way to pay for memory care. Selling your parents’ house to pay for memory care may make sense when the proceeds are needed for care and keeping the property no longer fits your family’s plans. Income, savings, insurance, benefits, family contributions, and home-equity options may also help cover expenses.
It’s understandable to look to the home first: it may be a major family asset, and deciding what to do with it can feel personal as well as financial. The right choice depends on your parent’s care needs, resources, and wishes, as well as who has legal authority to act if your parent can’t manage the sale.
This article explains when selling may be appropriate, how a power of attorney can affect the sale, and what funding alternatives families can consider. It also covers how to weigh the home’s role in a longer-term care plan before deciding.
Key Takeaways
- Weigh your parent’s care needs, available resources, and plans for the home before deciding whether a sale makes sense.
- Understand how the financial power of attorney’s specific authority can shape who may act in a home sale.
- Explore potential funding sources and understand how Medicaid estate recovery could affect the family home.
- Consider the timing of a sale in relation to care costs and your parent’s broader financial plan.
1. When to Sell a Parent’s Home for Senior Care
Yes, selling a parent’s house can help pay for memory care. It may make sense when the proceeds will support ongoing care and keeping the property no longer fits your parent’s plans. First, compare likely sale proceeds with care needs, income, savings, and other available resources. Dementia can make financial decisions harder, so involve your parent whenever possible and respect their preferences.
Care costs vary by location, community, and services. Compare what each memory care community includes and how support may change as needs grow. In-home care may suit a senior who needs less support, while memory care may better address dementia-related needs.
Consider alternatives before listing the home. According to the U.S. Department of Housing and Urban Development, eligible homeowners age 62 or older may consider a reverse mortgage to access home equity without selling immediately. Lenders often require repayment when the homeowner no longer lives there. A HELOC or home equity loan can also access equity, but review payment obligations, interest, taxes, insurance, fees, and estate goals. Bridge loans typically run 6 to 12 months; some require at least 20% home equity.
If dementia affects your parent’s capacity, confirm who can legally authorize a sale. A valid power of attorney may give an agent authority, depending on its terms. Without that authority, court permission may be needed; the process usually takes two weeks to a month. A legal professional can help clarify the appropriate process.
Taxes also affect the net proceeds. According to the Internal Revenue Service, a qualifying individual may exclude up to $250,000 of capital gain from U.S. income tax when selling a primary residence. A married couple filing jointly may qualify to exclude up to $500,000. Eligibility depends on tax rules.
A family home carries memories as well as equity. Discussing what your parent wants to keep, share, or pass on can make the decision more respectful and help relatives support the plan.
How can a real estate professional help sell a parent’s house if you have power of attorney?
A real estate professional can guide the home sale, but authority to sign for your parent must come first. The homeowner owns the property and must transfer it to the buyer, either personally or through an authorized agent. A power of attorney doesn’t automatically give every family member permission to sell a parent’s assets.
Review the financial power of attorney with an elder law attorney before listing. Its specific terms determine what the agent may do for the person who granted it. A general financial power of attorney may include authority to sell real property, but it must be valid and apply to the situation. A durable financial power of attorney can allow its named agent to act if the parent becomes incapacitated.
Memory impairment, including dementia or Alzheimer’s disease, can make it harder for a parent to understand or decide about a sale. If your parent can still make the decision, include them in discussions about timing, belongings, and their next home. If capacity or the agent’s authority is unclear, an elder law attorney can explain the legal options. Without a suitable power of attorney, a court process or guardianship may be necessary before someone can act.
Once authority is clear, a real estate professional can help establish the home’s market value, develop a sale plan, prepare the listing, coordinate showings, and manage offers through closing. You provide the power of attorney document and property details, and the agent coordinates transaction steps with the authorized signer. A financial advisor can help the family consider how sale proceeds fit the care plan, including assisted living or memory care payments.
The process can feel emotional, especially when relatives disagree about the home’s future. Keep decisions tied to your parent’s wishes and documented authority. For practical guidance through a senior home sale, work with a professional who understands the transition.
3. Can Families Pay for Memory Care Without Selling the House?
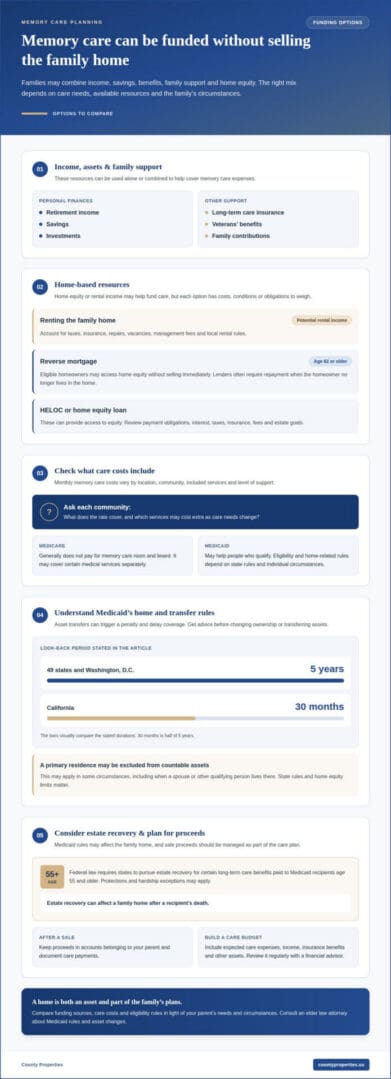
Yes. Families can combine retirement income, savings, investments, long-term care insurance, veterans’ benefits, family contributions, and home equity. Renting the family home may generate income, but account for taxes, insurance, repairs, vacancies, management fees, and local rental rules. A reverse mortgage may also provide access to equity, though its costs and repayment terms affect whether it’s appropriate.
Medicare generally doesn’t pay for memory care room and board, though it may cover certain medical services separately. Monthly memory care costs vary by location, community, included services, and level of support. Ask each community what its rate covers and which services may cost extra as care needs change.
Medicaid may help eligible people, but transferring assets can trigger a penalty and delay coverage. The Medicaid look-back period is five years in 49 states and Washington, D.C.; California’s period is 30 months. A primary residence may be excluded from countable assets in some circumstances, including when a spouse or other qualifying person lives there. State rules and home equity limits matter, so consult an elder law attorney before changing ownership or transferring assets.
According to the Centers for Medicare & Medicaid Services, federal law requires states to pursue estate recovery for certain long-term care benefits paid to Medicaid recipients age 55 and older, although protections and hardship exceptions may apply. Estate recovery can affect a family home after a recipient’s death. An advisor can help assess how eligibility, home equity, and family circumstances interact.
After a sale, keep the proceeds in accounts belonging to your parent and document care payments. Build a budget around expected care expenses, income, insurance benefits, and other assets, then review it regularly with a financial advisor. Don’t gift or retitle proceeds to qualify for Medicaid without legal guidance, because transfers may affect eligibility. Written records of withdrawals and payments help relatives track how the funds support care and protect your parent’s financial interests.
4. When to Sell a Parent’s House for Senior Care
Choose when to sell after clarifying the care plan and funding gap. Estimate ongoing care needs, your parent’s income and available assets, and likely sale proceeds. Compare these with expected care payments and the cost of keeping the home, including taxes, insurance, upkeep, and any outstanding mortgage. This helps show whether selling parents’ house to pay for memory care addresses a real shortfall or simply shifts the family’s resources. The decision should follow your parent’s plan, not just a move-in date.
Consider your parent’s preferences and whether anyone still relies on the property. If a spouse or relative lives there, selling could change their housing and finances. For veterans, a primary residence is generally excluded from the VA net-worth calculation, subject to VA rules. Proceeds from a sale may become countable and affect eligibility, so consider this change and its potential effect on benefits before deciding.
Timing also depends on the home’s condition and market value. A real estate professional or appraiser can estimate the value, while mortgage information helps clarify potential proceeds. Compare the estimate with expected care payments and the cost of retaining ownership. If the property needs work or is difficult to maintain, selling may simplify the transition. If care arrangements remain unsettled, waiting may preserve options, provided the family can manage the home in the meantime. For families considering selling parents’ house to pay for memory care, the practical question is whether the proceeds and timing fit the care plan.
Involve your parent in decisions about the home whenever they can participate. A family discussion can address belongings, ownership, and what the property means to them. Record the agreed plan, including how proceeds will support care and when the family will review the decision. A real estate professional can help assess the property and coordinate a sale around the care transition. To plan a sale alongside senior-care needs, work with a real estate professional.
County Properties
County Properties helps families plan a home sale as part of a parent’s move to memory care or another senior living arrangement. Turn to the team when you’re weighing whether to sell, preparing to list, or coordinating a sale with a care transition. Its Senior Real Estate Transition and Seller Representation services provide real estate guidance tailored to your family’s circumstances.
The team can help you understand the property’s market position, consider a sale strategy, and navigate the transaction with clear support. You and your family remain central to decisions about timing and the home’s future, while the sale process is handled with attention to your parent’s needs. For real estate guidance on your family’s next steps, contact County Properties.
Choose the Next Step With Your Parent in Mind
Selling your parents’ house to pay for memory care is more than a property decision. It’s a transition that can shape your parent’s routines, sense of home, and financial choices. Before moving forward, agree on what matters most: supporting care, preserving other options, or making a change that benefits the whole family. Keeping your parent involved can help the next step feel considered rather than rushed.
Once your family has a direction, a real estate professional can help turn that decision into a workable plan. County Properties provides Seller Representation and Buyer Representation, and can assist with Short Sale and Foreclosure Prevention when those needs affect the family’s plans. The right support keeps the property decision connected to the broader transition.
If you’re ready to discuss the home and your family’s next move, contact County Properties. A clear first conversation can help you move forward with care and confidence.
Frequently Asked Questions
Can Families Pay for Memory Care Without Selling the House?
Yes, families may use other resources or combine funding sources. Retirement income, savings, investments, long-term care insurance, veterans’ benefits, and family contributions can all help cover expenses. Renting the home or using home equity may also be options, but each affects the family’s finances differently. Consider how long funds may last and whether anyone depends on the home before choosing.
Can a person with dementia sell their house?
A person with dementia may sell their home if they can make and communicate the decision and complete the transaction. A diagnosis alone doesn’t determine who may sign for the owner. If memory changes affect decision-making, clarify the person’s legal authority before proceeding. A real estate professional can coordinate the sale but cannot replace the owner’s or an authorized representative’s decision.
What are some other ways to pay for long-term care?
Possible funding sources include income, savings, investments, long-term care insurance, veterans’ benefits, family contributions, and home equity. Insurance coverage depends on the policy; some providers require medical records, an assessment, or proof that the person needs help with daily routines. Medicare generally doesn’t cover memory care room and board, though certain medical services may be covered separately. Review policy requirements early to understand the claims process.
When Is the Right Time to Sell Your Parent’s Home to Pay for Senior Care?
Consider selling when the care plan is clear and the home’s ongoing costs or responsibilities no longer fit your parent’s circumstances. Compare likely proceeds with care needs, income, and other available resources. Also consider whether a spouse or relative relies on the home, and whether your parent can take part in the decision. The timing should support the care transition without rushing important family choices.
How can you sell a parent’s house if you have power of attorney?
Start by reviewing the power of attorney document to see whether it authorizes the named agent to sell real property. The agent may then coordinate with a real estate professional and sign for the homeowner only within that authority. Keep the document available during the transaction, and ensure the agent’s actions serve the parent’s interests. If the document’s scope is unclear, seek guidance from an elder law attorney.
Who needs legal authority to sell the home?
The homeowner can sell and transfer the property, or an authorized representative can act on the owner’s behalf. A child or other relative doesn’t gain authority simply through family ties. A valid power of attorney may authorize an agent, depending on its terms. If no suitable authority exists and the owner can’t act, a court process may be required to appoint someone who can manage the sale.