To judge whether you’re overpaying for a Del Mar property, compare it with similar homes that closed in the past 6 months. The fear of making a mistake in the San Diego real estate market can ease when you weigh recent comparable sales alongside the property’s condition and your plans for it. A home’s asking price alone doesn’t tell you whether it’s fair.
It’s understandable to worry about paying too much or losing your deposit if an inspection uncovers costly work. This guide explains how to assess a Del Mar property’s price and use contingency periods to help protect your deposit. You’ll also learn what to review before making an offer, how to evaluate a renovation property during the inspection period, and which first-time buyer missteps can make it harder to decide with confidence.
Key Takeaways
- Compare a Del Mar home with similar properties that closed in the past 6 months, rather than relying on the asking price alone.
- Assess the property’s condition and your long-term plans alongside comparable sales to make a more grounded offer decision.
- For a renovation project, arrange a contractor walk-through and rough scope estimate during the inspection contingency period, before removing contingencies.
- Start jumbo-loan pre-approval before touring homes so you’re prepared to make a credible offer when you find the right property.
- Use contingency periods thoughtfully to evaluate key risks and help protect your deposit.
1. How do I know if I’m overpaying for a Del Mar property?
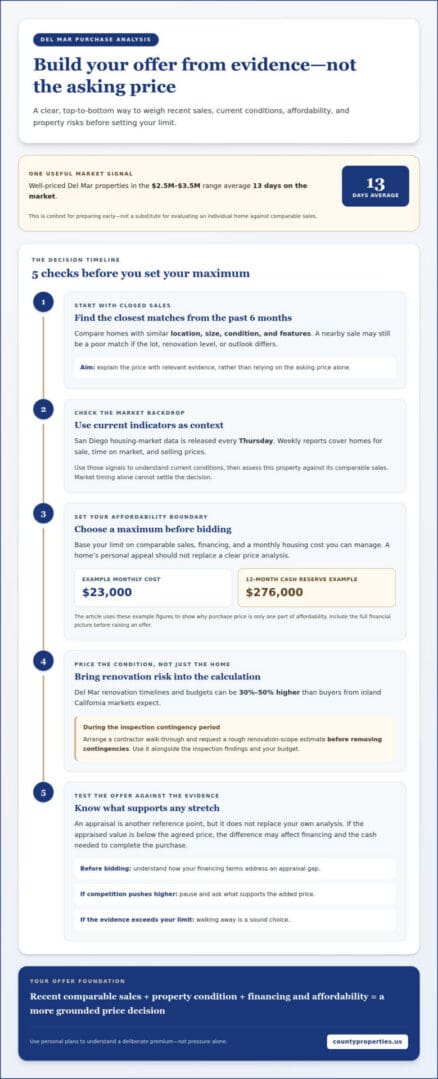
Start with closed sales, not the asking price. For a Del Mar property, compare it with similar homes sold during the past 6 months. Focus on homes with comparable location, size, condition, and features. A nearby sale can still be a poor match if it has a different lot, renovation level, or outlook. The goal is to explain the price through relevant evidence.
Then look at how the asking price compares with that range. A high asking price does not prove a home is overpriced, and a low one does not guarantee value. Check whether the home’s condition or features justify a difference from similar sales. Well-priced Del Mar properties in the $2.5 million to $3.5 million range average 13 days on the market, so buyers should prepare their analysis before finding a home they want.
Fear of making a mistake in the San Diego real estate market can make waiting feel safer. But waiting for every uncertainty to disappear can mean missing a home that fits your needs and budget. San Diego housing-market data is released every Thursday, with weekly reports on homes for sale, time on market, and selling prices. Use those indicators to understand current conditions, then assess each property against comparable sales.
Set your decision range before a bidding war begins. Choose a maximum purchase price based on comparable sales, your financing, and the monthly housing cost you can manage. If competing buyers push the offer above your range, pause and ask what supports the higher price. A home’s personal appeal matters, but it should not replace a clear price analysis.
- Compare: Match the property with similar closed sales from the past 6 months.
- Investigate: Account for condition, location, and features that explain price differences.
- Set a limit: Decide your maximum before bidding, using both market evidence and affordability.
The example also uses a $23,000 monthly housing cost to calculate a 12-month cash reserve requirement of $276,000. These figures show why the purchase price is only one part of affordability. Include the full financial picture before raising your offer.
An appraisal can provide another reference point, but it does not replace your own price analysis. If the appraised value is below the agreed purchase price, the difference may affect financing and the cash needed to complete the purchase. Before bidding, understand how your financing terms address an appraisal gap. Compare the appraisal with the property details and sales evidence you used to set your offer.
For a renovation property, include the likely work in your price assessment. Del Mar renovation timelines and budgets can be 30% to 50% higher than buyers from inland California markets expect. During the inspection contingency period, arrange a contractor walk-through and rough renovation scope estimate before removing contingencies. That step helps you evaluate the purchase price alongside the work, rather than treating the home’s current condition as a minor detail.
A disciplined decision does not require predicting every market change. Use recent closed sales, weekly San Diego market indicators, financing limits, and the property’s condition to support your offer. If the evidence points to a price above your range, walking away is a sound choice. If comparable sales and your financial plan support the purchase, delaying solely out of fear can also have a cost.
Paying a premium can be a deliberate choice when it reflects your long-term plans rather than pressure in a bidding contest. Paying slightly above market value for a coastal San Diego home may be reasonable for buyers who plan to live there for many years through County Properties. That does not establish what every Del Mar home is worth. Local comparable sales and your budget should guide that judgment. If you choose to stretch, be clear about why the property merits the added cost and whether your long-term plans make the trade-off comfortable.
In competitive coastal markets, offers were often six figures over the asking price during peak housing periods. Local buyers frequently pause their home searches when unexpected spikes occur, expecting the market to settle down. Buyers navigating families and career shifts face similar timing dilemmas across the region. These experiences illustrate why market timing alone cannot settle a personal decision. They are not Del Mar price evidence, so use them as context rather than as a reason to exceed the limit supported by your own analysis.
2. Using contingency periods to protect deposits
A contingency period gives you time to investigate a purchase before making key decisions. The offer’s written terms set the relevant conditions, deadlines, and required notices. Read those terms before signing, then add each date to your calendar. A clear timeline helps you use the review period deliberately, rather than treating it as open-ended time to reconsider the entire purchase.
Start by identifying what each contingency allows you to assess. For an inspection contingency, schedule the inspection promptly and review the findings while there’s still time to respond. If the property needs work, note which repairs affect safety, function, or your renovation budget. Keep the inspection report, contractor notes, and questions together so your decision reflects the property’s actual condition.
For a renovation property, arrange a contractor walk-through and request a rough renovation-scope estimate during the inspection contingency period, before removing contingencies. Use the estimate to understand the work involved, not as a replacement for an inspection. Visible cosmetic updates, for example, may exist alongside underlying issues that change the project’s scope. Compare the expected work with your budget and intended use.
Address financing and appraisal concerns early, too. Track the documents your lender needs, respond promptly, and keep the financing timeline visible alongside contingency deadlines. An appraisal provides a value opinion for the lender’s process, while your comparable-sales review helps inform your offer. If the appraisal differs from the purchase price, revisit your financing terms and available funds before deciding what to do next.
Deposit protection depends on following the process stated in the offer, not simply on having a contingency in writing. Note each deadline and any required written communication. Keep copies of notices and reports, and send decisions through the channels described in the agreement. If you need more time, raise the issue before the deadline and document any agreed change in writing. Clear records help prevent confusion about what happened and when.
Keep a simple working file for the transaction. Include the signed offer, contingency dates, inspection materials, lender requests, appraisal information, and communications about changes. Review it whenever new information affects your decision. A contractor’s scope estimate, for example, could prompt you to reconsider the renovation plan, while a lender update could affect your financing strategy. Make one decision at a time, based on the relevant information.
Removing a contingency is a significant decision because it changes the protections available under the agreed terms. Before taking that step, confirm that the related review is complete and that you understand any unresolved issues. Use a checklist: inspection reviewed, renovation scope considered, financing status understood, and deadline recorded. Don’t remove a contingency just to make your offer seem stronger without weighing what remains uncertain.
In a competitive market, buyers may feel pressured to shorten the review period or waive a contingency. Decide in advance which reviews matter most and what information you need before proceeding. Faster decisions are useful only when they’re informed. A documented inspection, timely communication with your lender, and clear deadline tracking provide a more disciplined basis for action than urgency alone.
If a purchase is part of a broader move, keep the timing of your housing decisions connected. A coordinated senior real estate transition can help frame sale and purchase planning around the same move. For this property, though, focus first on the written contingency terms, the inspection findings, and any contractor scope estimate. Those steps make the review period practical and purposeful.
3. What mistakes do first-time homebuyers make in San Diego?
One costly mistake is touring Del Mar homes before understanding the financing process. Buyers who tour Del Mar properties for two weeks without jumbo pre-approval may be unable to make a credible offer when they find a home they want. Start lender discussions 60 to 90 days before you plan to make an offer. That gives you time to organize financial documents and understand your borrowing options before a property captures your attention.
A correctly completed Del Mar jumbo-loan pre-approval process takes 5 to 10 business days. Treat that as a preparation step, not a last-minute task after finding a home. Ask your lender what documents are needed, submit them promptly, and follow up on outstanding requests. Pre-approval helps you understand your financing position, but it doesn’t replace a property-specific review or mean you should offer more than your budget supports.
Another mistake is focusing only on the listing price. For a Del Mar home, compare the property with similar closed sales from the past 6 months, then consider condition, location, and features. A home that appears to be a bargain may need substantial work. A higher-priced property may have features that explain the difference. Write down what supports the price before deciding what to offer.
First-time buyers can also let bidding pressure make the decision for them. Before submitting an offer, set a maximum based on your financing and housing budget. If competition pushes the price beyond that limit, pause and compare the new offer amount with recent sales. Decide in advance which features justify flexibility and which financial boundaries remain firm. A clear limit keeps urgency from becoming the only reason to raise your bid.
- Before touring: Begin lender discussions early and gather requested documents.
- Before offering: Compare the home with recent sales and identify price-supporting features.
- During competition: Keep a written maximum offer and revisit it before increasing your bid.
Skipping a careful review of the home’s condition is another avoidable error. For a renovation property in Del Mar, arrange a contractor walk-through and rough scope estimate during the inspection contingency period. Del Mar renovation timelines and budgets can be 30% to 50% higher than buyers from inland California markets expect. Use the estimate to consider the work alongside the purchase price, rather than assuming visible updates tell the whole story.
Some buyers mistake a lender’s appraisal for a complete judgment of a home’s value. An appraisal is part of the financing process; your comparison of recent closed sales helps you assess the offer. If the appraisal differs from the agreed price, understand how that difference affects your financing and available funds. Discuss the implications with your lender before deciding how to proceed.
Finally, don’t let fear of an imperfect choice turn into endless searching. Make a short list of needs, such as location, usable space, condition, and travel routines. Then assess each San Diego property against that list and your financial plan. If a Del Mar home meets your essential needs but needs cosmetic work, for example, distinguish those updates from repairs that could change your budget or plans.
Prepare your priorities, financing questions, and offer limits before the next showing. Plan your San Diego home purchase with a clear set of criteria, so each decision builds on the information you’ve gathered.
A lender’s appraisal is not a reason to stop assessing whether a home fits your needs. Treat it as one consideration, alongside the property, likely work, and amount you are prepared to spend. Homes generally appreciate over time, but that broad expectation is no reason to overlook condition or exceed a comfortable budget. Base your decision on the home in front of you and the costs you can manage, rather than assuming future appreciation will resolve your concerns.
Orange County homebuyers can use contingency periods to help protect their deposits. Track the choices and deadlines that apply to your purchase, and make time to review concerns before deciding whether to proceed. In San Diego, the same careful approach can help first-time buyers avoid treating a deposit as a reason to move forward while important questions remain. Bring unresolved concerns to the appropriate professionals, weigh their guidance against your budget, and decide deliberately. Preparation, realistic cost estimates, and firm financial boundaries can help keep the purchase aligned with your priorities.
County Properties: Seller Representation
County Properties provides Buyer Representation for San Diego buyers seeking structured guidance as they compare properties, prepare offers, and track contingency deadlines. This support can help you organize comparable sales, inspection findings, financing considerations, and offer terms as you make decisions. If you’re selling as part of a move, Seller Representation can guide that side of the transaction. Senior Real Estate Transition may also suit a move prompted by changing housing needs.
Choose support that matches your next step: buying, selling, or coordinating a transition. Clear priorities and timely communication can help you approach each decision with greater focus.
Contact County Properties or visit countyproperties.us to discuss your real estate needs.
Move Forward With a Clear Plan
A real estate decision doesn’t need to be flawless to be thoughtful. Turn what matters most into a practical plan: define your priorities, identify the questions you still need answered, and decide what would make you pause. This gives you a steady point of reference as circumstances change.
If fear of making a mistake in the San Diego real estate market is holding you back, focused guidance can help you move from uncertainty toward an informed decision. County Properties offers Buyer Representation and Seller Representation, as well as Short Sale and Foreclosure Prevention for homeowners facing financial pressure. The right support depends on the real estate challenge you’re working through.
Take the next step at your pace. Contact County Properties to discuss your purchase and explore a path forward that fits your goals. With a clear plan and dependable guidance, you can approach your next move with greater confidence.
Frequently Asked Questions
How do I know if I’m overpaying for a Del Mar property?
Compare the home with recent closed sales similar in location, condition, size, and features, then investigate major price differences. A remodeled home and one needing substantial work, for example, may not be comparable even if they’re nearby. Consider whether the asking price also fits your intended use and financing plan. A written comparison helps distinguish a supported premium from a price driven mainly by competition.
What contingencies should San Diego homebuyers include in an offer?
Consider contingencies that give you time to assess the property, financing, and appraisal, with terms and deadlines clearly stated in the offer. An inspection contingency can allow you to investigate the home’s condition; a financing contingency can address loan approval; and an appraisal contingency can address a value below the agreed price. Choose terms based on your transaction priorities, and track every deadline so you can act within the agreed timeline.
What steps can reduce the risk of overpaying for a San Diego home?
Set a maximum offer before negotiations, based on comparable sales and what you can comfortably afford. Review the property’s condition and likely repairs, and separate essential needs from upgrades you can postpone. Before increasing an offer, identify what new information supports the higher price. If an appraisal differs from your offer, understand the effect on your financing and available funds before proceeding. These steps help keep emotion from setting the purchase price.